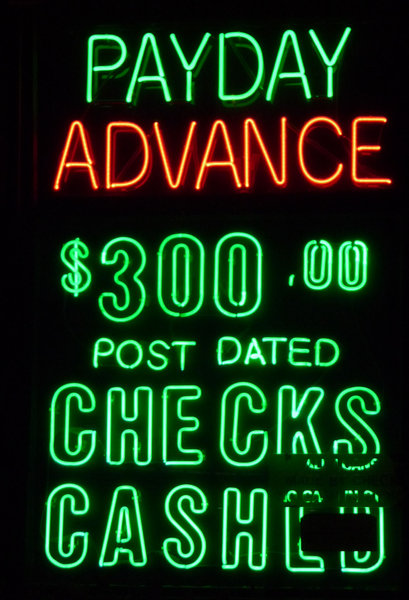
(Image: http://a.rgbimg.com/cache1qcWfP/users/d/do/dotlizard/600/mWIHArk.jpg) Payday loans have emerged as a controversial financial product, offering fast access to cash for individuals who find themselves in pressing want of funds. These loans, typically starting from $one hundred to $1,000, are characterized by excessive curiosity rates and quick repayment durations, usually aligned with the borrower's subsequent paycheck. This text goals to dissect the structure, implications, and potential options to payday loans, whereas highlighting their socio-economic influence on borrowers.
Understanding Payday Loans
Payday loans, typically marketed as a convenient solution to unexpected expenses, are designed for brief-time period borrowing. These loans are sometimes unsecured, meaning that borrowers do not want to offer collateral. The appliance process is mostly simple: borrowers can apply online or in-retailer, often with no credit check, thus appealing to a demographic which will have limited access to traditional lending options because of poor credit histories.
The loan agreement often stipulates that the borrower must repay the loan in full, together with interest and charges, by their subsequent payday. The typical annual proportion charge (APR) for payday loans can exceed 400%, a staggering figure when compared to typical credit score products. Whereas this excessive cost of borrowing permits payday lenders to revenue, it locations considerable monetary strain on borrowers, significantly those from decrease-earnings backgrounds who could already be struggling with financial instability.
The Socio-Financial Impact of Payday Loans
The implications of payday loans extend beyond individual borrowers, affecting families and communities at giant. Whereas these loans provide immediate relief in financial emergencies, the lengthy-time period penalties will be devastating. Analysis indicates that many borrowers resort to payday loans on account of a lack of savings or financial literacy. Consequently, they usually discover themselves in a cycle of debt; unable to repay the original loan, they take out additional loans, incurring extra fees and curiosity.
This cycle can result in a phenomenon known as “debt traps,” the place borrowers change into entangled in an online of loans, diminishing their potential to satisfy primary dwelling bills and doubtlessly resulting in bankruptcy or other monetary distress. The reliance on payday loans highlights systemic issues resembling earnings inequality and lack of entry to affordable credit options. In the United States, research have shown that payday loan usage is disproportionately high in communities with limited entry to banking providers, additional entrenching financial disparity.
Legislative Panorama: Regulation and Reform
The payday lending industry has confronted growing scrutiny from policymakers and client advocacy groups, which argue for stricter laws to guard weak borrowers. In the United States, several states have enacted laws to restrict the interest rates and charges related to payday loans. However, enforcement of such laws can range significantly from one jurisdiction to a different.
The consumer Financial Protection Bureau (CFPB) launched guidelines aimed at curbing predatory lending practices, mandating lenders to assess a borrower’s capability to repay earlier than extending a loan. When you have any issues concerning exactly where in addition to how to utilize Emergency loan options, you'll be able to contact us on the site. Despite these efforts, the payday lending industry has been in a position to use loopholes and adapt to regulatory changes, continuing to serve as a supply of credit for millions of People. This ongoing tug-of-struggle between client protection and the payday lending business raises critical questions concerning the effectiveness of regulation and the need for comprehensive reform.
Alternate options to Payday Loans
Given the potential perils of payday loans, it is crucial to discover various financial solutions that may provide borrowers with much less detrimental options. Entry to reasonably priced credit and financial education is important in helping consumers to make knowledgeable selections about their borrowing wants.
Credit score Unions and Neighborhood Banks: Not like payday lenders, credit score unions and group banks often provide small personal loans with lower interest charges and more versatile repayment phrases. These establishments usually emphasize member service and community development, making them a extra sustainable possibility for individuals searching for credit.
Installment Loans: Moderately than requiring full repayment by the next payday, installment loans enable borrowers to repay the loan in smaller, more manageable increments over an extended interval. While these loans can still carry important interest charges, the construction reduces the chance of default and encourages accountable borrowing.
Employer-Sponsored Loan Packages: Some employers provide packages that enable employees to entry earned wages earlier than their official payday. Such advances might help alleviate financial emergencies with out subjecting employees to the high prices related to payday loans.
Monetary Schooling: Selling monetary literacy through group workshops and online assets can empower people to handle their finances better and avoid predatory lending practices. Understanding budgeting, savings, and credit score might be instrumental in breaking the payday loan cycle.
Government Help Applications: Many native and state governments provide help packages designed to help people in financial distress. These packages can embrace food assistance, housing assistance, and other forms of assist that may reduce the need for fast cash borrowing.
Conclusion
Payday loans signify a complex intersection of monetary necessity and predatory practice. Whereas they offer speedy relief to borrowers going through pressing financial crises, the lengthy-time period repercussions could be extreme, perpetuating cycles of debt and financial instability. Addressing this problem requires a multifaceted method that includes stricter regulations, elevated access to various lending options, and enhanced monetary literacy education.
In an era the place financial wellness is critical for particular person and communal growth, it is essential to empower customers with information and assets that enable them to make informed financial selections. As policymakers and community leaders grapple with the implications of payday lending, fostering a extra equitable financial panorama will remain a pressing challenge that warrants consideration and motion.
(Image: http://a.rgbimg.com/cache1qcWfP/users/d/do/dotlizard/600/mWIHArk.jpg)